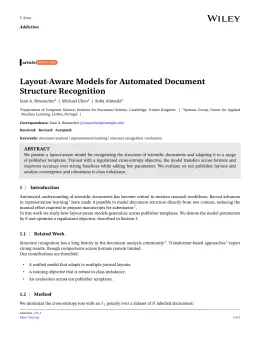
About the Quantitative Finance format
Quantitative Finance is a peer-reviewed journal published by Taylor & Francis, covering Stochastic processes and financial applications, Financial Risk and Volatility Modeling, Financial Markets and Investment Strategies. Over its lifetime it has published 3,173 papers, which have received 73,568 citations.
| Publisher | Taylor & Francis |
|---|
| Reference style | Author–year (Chicago, T&F) Author–year — (Smith, 2023) in the text
Smith, Ada, Ben Jones, and Cara Lee. 2023. "A Representative Article Title." Quantitative Finance 12 (3): 45–58.
Formats any DOI in Quantitative Finance style. No sign-up.
|
|---|
| Publishes research in | Stochastic processes and financial applications Financial Risk and Volatility Modeling Financial Markets and Investment Strategies Complex Systems and Time Series Analysis Market Dynamics and Volatility |
|---|
| ISSN | 1469-7688 |
|---|
| Citation impact (2-yr) | 2.26 |
|---|
| h-index | 113 |
|---|
| i10-index | 1,299 |
|---|
| Top institutions publishing here | Centre National de la Recherche Scientifique |
|---|
| Journal website | www.tandfonline.com |
|---|
| You get | A submission-ready PDF and the editable LaTeX source — ready to submit. |
|---|
Papers published in Quantitative Finance per year
Citation impact of Quantitative Finance by publication year
Citations each year’s papers have accumulated so far — the most recent years are still building up.
Most-cited papers in Quantitative Finance
Empirical properties of asset returns: stylized facts and statistical issues
Rama Cont · 1 Feb 2001
We present a set of stylized empirical facts emerging from the statistical analysis of price variations in various types of financial markets. We first discuss some general issues common to all statistical studies of financial time series. Various statistical properties of asset returns are then described: distributional properties, tail properties and extreme fluctuations, pathwise regularity,…
Network topology of the interbank market
Michael Boss, Helmut Elsinger, Martin Summer et al. · 1 Dec 2004
We provide an empirical analysis of the network structure of the Austrian interbank market based on Austrian Central Bank (OeNB) data. The interbank market is interpreted as a network where banks are nodes and the claims and liabilities between banks define the links. This allows us to apply methods from general network theory. We find…
What good is a volatility model?
Robert F. Engle, Andrew J. Patton · 1 Feb 2001
A volatility model must be able to forecast volatility; this is the central requirement in almost all financial applications. In this paper we outline some stylised facts about volatility that should be incorporated in a model; pronounced persistence and meanreversion, asymmetry such that the sign of an innovation also affects volatility and the possibility of…
Empirical modelling of contagion: a review of methodologies
Mardi Dungey, Renée Fry-McKibbin, Brenda González‐Hermosillo et al. · 1 Feb 2005
There is now a reasonably large body of empirical work \ntesting for the existence of contagion during financial \ncrises. A range of different methodologies are in use, \nmaking it difficult to assess the evidence for and against \ncontagion, and particularly its significance in transmitting \ncrises between countries. The origins of current empirical \nstudies of contagion stem from Sharpe (1964) and Grubel \nand…
Empirical properties of asset returns: stylized facts and statistical issues
Rama Cont · 1 Feb 2001
Abstract We present a set of stylized empirical facts emerging from the statistical analysis of price variations in various types of financial markets. We first discuss some general issues common to all statistical studies of financial time series. Various statistical properties of asset returns are then described: distributional properties, tail properties and extreme fluctuations, pathwise…